

 Facebook
 X
 Pinterest
 Copy Link
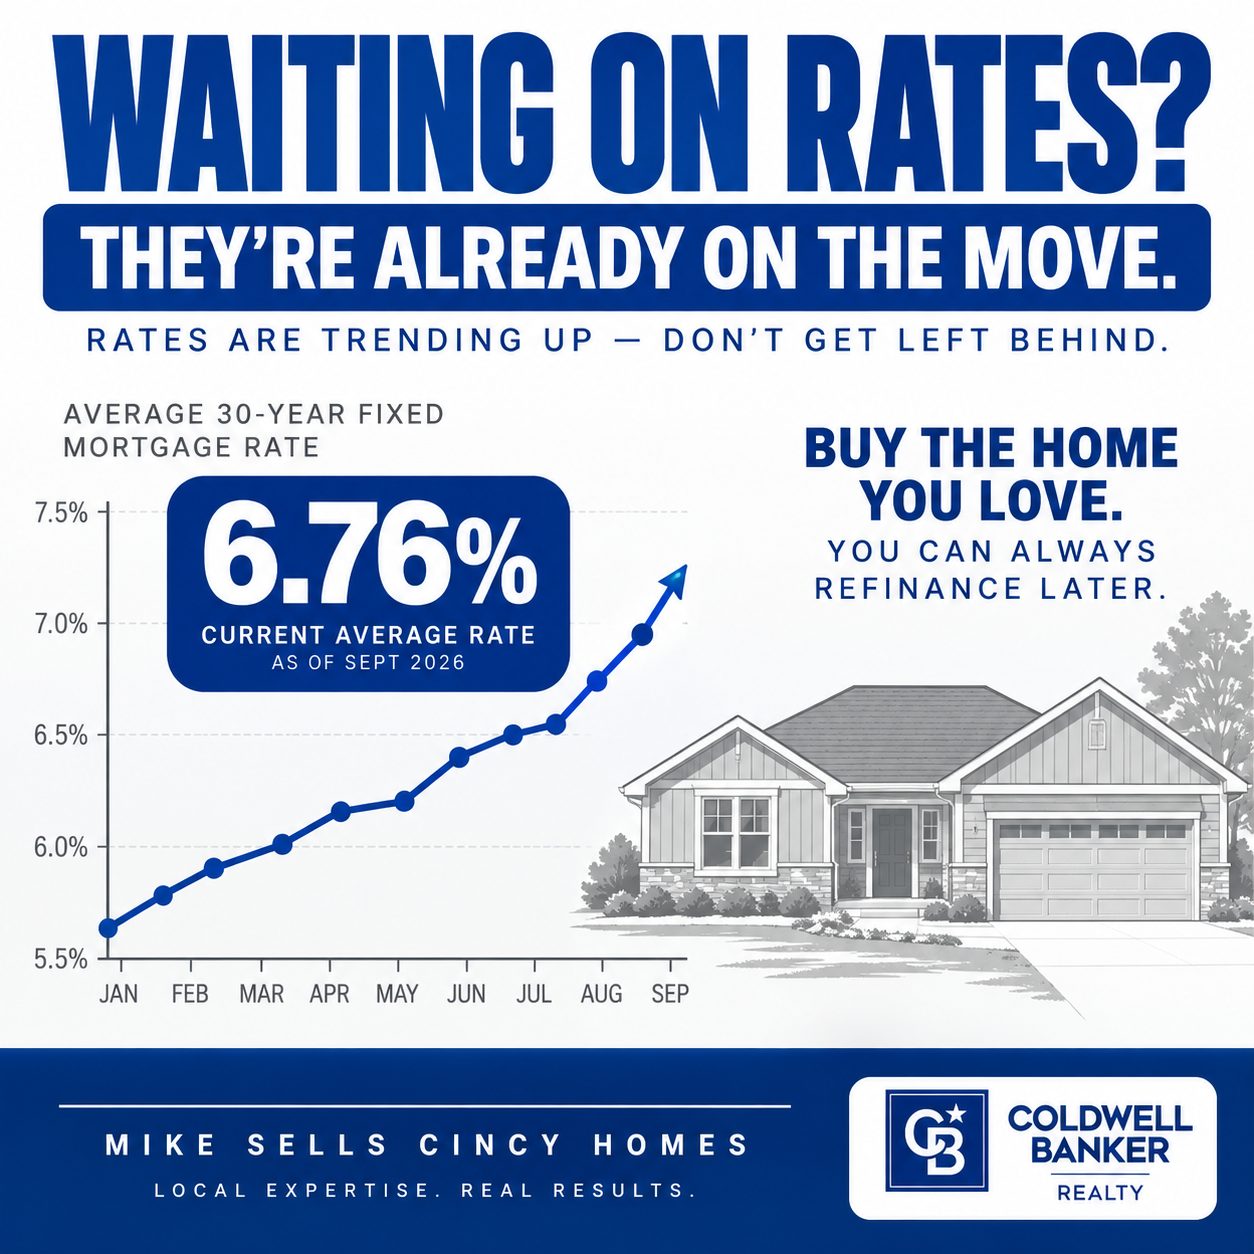
If you own a home in Loveland and you’ve been waiting for “the right time” to sell, here’s the uncomfortable truth: waiting on mortgage rates to make the decision for you might be costing you more than it’s saving you. 🏡 Whether you’re downsizing, relocating, or just testing the waters, the question of whether to sell your Loveland home before rates change deserves a real answer built on data, not a guess based on what rates “might” do next year.
Let’s break down what’s actually happening with mortgage rates, what it means for you as a seller, and how to make a call you won’t second-guess six months from now.
Quick Answer
Mortgage rates have actually been rising, not falling, heading into fall 2026, currently sitting around 6.76% on a 30-year fixed loan. Waiting for rates to drop before you sell your Loveland home isn’t a guaranteed strategy, and it can mean sitting on a decision while buyer demand and local pricing keep shifting. For most Loveland sellers, the smarter move is pricing and timing around today’s real market data, not a rate forecast nobody can promise.
Why This Question Matters Right Now
Every seller wants to time the market perfectly. It makes sense. Nobody wants to leave money on the table or list into a slow stretch.
But here’s what I see constantly as an agent working the East Side: sellers who “wait for rates to drop” often end up waiting well past the window when their home would have sold fastest and for the strongest price. Rates are one input. They’re not the whole equation, and they’re not something any of us can control or predict with certainty.
The better question isn’t “where will rates go?” It’s “what does my home, my timeline, and my equity position look like today, and does that timeline still make sense in six or twelve months?”
Key Trends & Data
Here’s where things actually stand, based on the most recent numbers available:
- 📊 The 30-year fixed mortgage rate is averaging around 6.76% as of early September 2026, up from 6.71% the week before, and up from 6.35% a year earlier, according to Freddie Mac’s Primary Mortgage Market Survey.
- Rates have trended upward through the summer rather than the decline many buyers and sellers were hoping for.
- Regionally, the Greater Cincinnati market has seen median sold prices climb, alongside a meaningful jump in active inventory compared to a year ago, which tells us buyers have more to choose from than they did last year.
- Homes in the region have continued to move at a healthy pace, though not as fast as the peak of the pandemic-era market.
The takeaway: if you’ve been holding out for rates to drop before you sell, that strategy hasn’t paid off this year, and there’s no reliable signal that it will next quarter either.
Buyer & Seller Motivation Insights
Buyers right now are motivated, but they’re also more selective. Higher borrowing costs mean today’s buyer is doing real math on their monthly payment, so a well-priced, well-presented home stands out fast against one that’s overpriced or needs work.
Sellers, meanwhile, are often juggling two questions at once: what will my home sell for, and what will it cost me to buy my next place? That’s especially true for anyone downsizing or moving within Loveland. If you’re selling and buying, rate movement affects both sides of your transaction, so it’s worth running the numbers on your full move, not just the sale.
👉 Curious what your Loveland home could sell for in today’s market? Take a look at current activity in the Loveland market and see how your home compares before you decide on timing.
Popular Features & Lifestyle Trends
Buyers touring homes in Loveland right now consistently gravitate toward a few features:
- Open-concept kitchen and living spaces
- Updated, low-maintenance flooring
- One-story or primary-bedroom-on-main layouts
- Flexible bonus rooms (home office, gym, or den)
- Low-maintenance outdoor living space
None of this is a surprise. Buyers want a home that’s ready to move into without a long list of projects, and they’re willing to move quickly on the ones that check those boxes.
Local Market Insights: Loveland & the East Side
Loveland continues to draw buyers for straightforward, practical reasons: easy access to the Little Miami Scenic Trail, a walkable historic downtown with local shops and restaurants, and a mix of housing styles that range from ranch homes to newer builds in the surrounding subdivisions.
Commute routes into Cincinnati via I-275 and Ohio-48 remain a draw for buyers relocating from outside the region, and the broader East Side, including Milford, Miami Township, and Symmes Township, continues to see steady buyer interest tied to those same logistics: access, walkability, and a mix of home styles at different price points.
If you’re weighing whether your specific block or subdivision is seeing strong activity, that’s a conversation worth having before you set a listing date, not after.
Financial & Lending Considerations
At 6.76%, the math on a $350,000 mortgage looks a lot different than it did when rates were near 3%, and that’s exactly why pricing strategy matters more than ever. Overpricing a home in this rate environment tends to backfire fast, since buyers are already stretching their budgets and have less room to negotiate up.
If you’re selling and buying, ask your lender about bridge financing or contingent-offer strategies so a rate shift doesn’t leave you stuck between two homes. And if you’re downsizing, run the numbers on what a smaller mortgage (or no mortgage at all) does for your monthly budget. That shift alone can outweigh whatever a rate change does or doesn’t do.
Actionable Tips For Loveland Sellers
- Get a real value estimate, not a generic online guess, before you set expectations.
- Talk to a lender early if you’re buying your next home, so you know your numbers before you list.
- Price to today’s market, not to what your neighbor’s house sold for two years ago.
- Handle small repairs first. Buyers notice deferred maintenance immediately in a rate-sensitive market.
- Set a realistic timeline based on your life, not a rate prediction you can’t control.
Pro REALTOR® Strategy: What Most Sellers Overlook
Here’s what most sellers miss: the biggest lever you control isn’t the rate environment, it’s your pricing and presentation strategy. I’ve watched two nearly identical homes in the same Loveland neighborhood get completely different results, purely because one was priced and marketed to match current buyer behavior and the other wasn’t.
Instead of trying to predict the Fed, I build a pricing strategy around what’s actually happening on the ground: current comparable sales, how many similar homes are competing with yours right now, and how buyers in your specific price range are behaving this month. That’s a strategy you can act on today.
Frequently Asked Questions
Should I wait for mortgage rates to drop before selling my house?
Not necessarily. Rates have moved up over the past year rather than down, so waiting on a rate drop isn’t a guaranteed strategy. It often makes more sense to evaluate your home’s value and local buyer demand today.
How do mortgage rates affect home sellers, not just buyers?
Rates affect how much buyers can afford to offer, which shapes your pool of potential buyers and how they negotiate. If you’re also buying your next home, rates affect your own purchasing power too.
Is now a good time to sell a home in Loveland, Ohio?
It depends on your home’s condition, your equity position, and how it’s priced against current comparable listings. A local market evaluation is the best way to answer this for your specific property.
Will home prices drop if mortgage rates come down?
There’s no guaranteed relationship between rates and prices. Lower rates can increase buyer demand, which has historically supported prices rather than pushed them down, but no outcome can be promised.
How long does it typically take to sell a home in the Loveland area?
Timelines vary by price point, condition, and how a home is marketed. A local pricing and marketing strategy has more influence on your timeline than rate movement does.
Should I sell before or after I refinance or pay down my mortgage?
This depends on your individual loan terms and equity. It’s worth a conversation with your lender and your agent together before you decide.
Should downsizers wait to sell?
Not automatically. For many downsizers, the monthly savings from a smaller home or smaller mortgage outweighs any wait-and-see rate strategy. It’s worth running your specific numbers rather than guessing.
Bottom Line
Trying to time your sale around where mortgage rates might go is a guessing game, and it’s one that hasn’t paid off for sellers who waited through 2026. If you’re thinking about whether to sell your Loveland home now or later, the better move is building a strategy around your equity, your timeline, and what’s actually happening in the Loveland market today.
I’d rather walk you through real numbers than have you guess based on a headline. Schedule a quick call and let’s look at what your specific situation looks like.
Ready to take the next step?
📞 Schedule a Free 30-Minute Consultation
🏡 Find Out What Your Home Is Worth
🔎 Search Clermont County Homes
📬 Subscribe to the Blog
Sources: National Association of REALTORS®, Freddie Mac Primary Mortgage Market Survey
