

 Facebook
 X
 Pinterest
 Copy Link
If you’ve been renting in Milford, Batavia, or anywhere else on Cincinnati’s East Side and wondering whether homeownership is actually within reach, here’s some good news: you can buy a home with 3% down in Clermont County, and you don’t need a massive savings account or spotless credit to make it happen. 🏡 Low down payment loan programs have quietly become one of the most useful tools for first-time buyers in 2026, yet most renters have no idea they exist. Let’s walk through how a 3% down payment actually works, what it costs in real numbers, and whether it’s the right move for you.
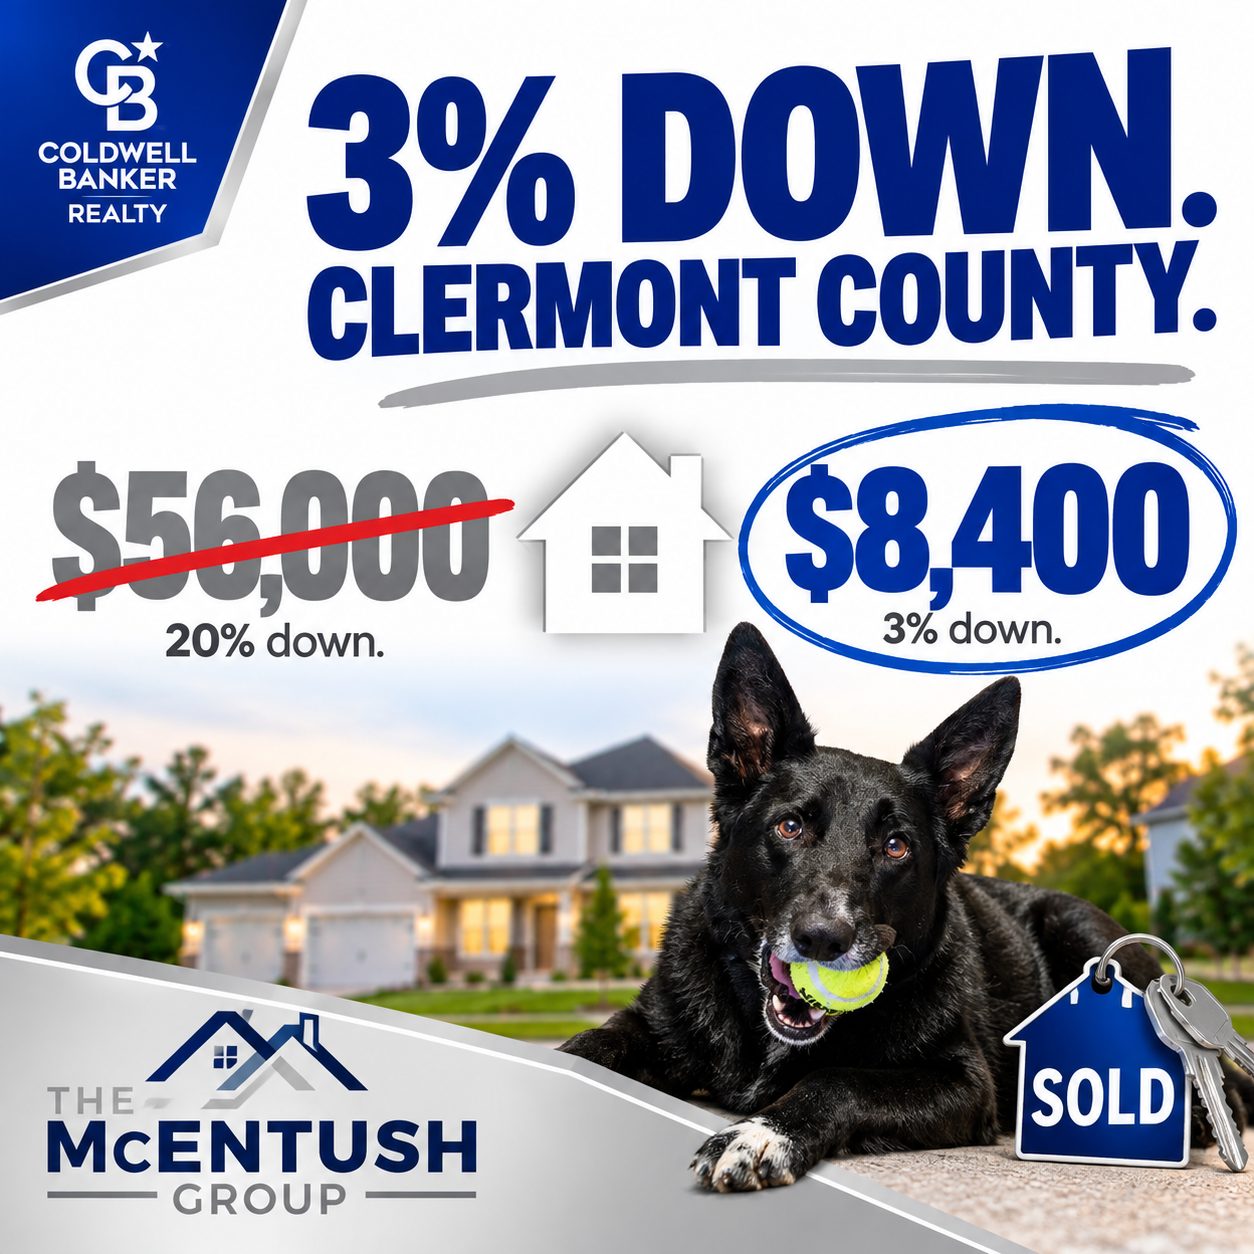
Quick Answer: Yes — you can buy a home with 3% down in Clermont County through loan programs like Conventional 97 and FHA. On a $280,000 home, that’s roughly $8,400 down instead of the $56,000 many renters assume is required for 20% down. You’ll carry mortgage insurance until you build enough equity, but for most first-time buyers, moving into a home sooner outweighs that added monthly cost.
Why This Question Matters Right Now
Rent across Clermont County and the broader East Side has climbed steadily over the past few years, while mortgage rates have settled into a more workable range compared to where they peaked. That combination changes the math for a lot of renters. Instead of asking “can I ever save 20%?”, more buyers are asking “what’s the fastest responsible path to owning something?” A 3% down payment is often that path, especially for buyers who are otherwise financially ready but have been held back by the down payment myth alone.
The Numbers: What 3% Down Actually Looks Like
Here’s a side-by-side look at what changes when you move from the “traditional” 20% down payment to a 3% down payment:
- $280,000 home, 20% down: $56,000 cash needed at closing
- $280,000 home, 3% down: $8,400 cash needed at closing
- $350,000 home, 20% down: $70,000 cash needed
- $350,000 home, 3% down: $10,500 cash needed
That’s tens of thousands of dollars of difference — often the exact gap between “someday” and “this year.” Freddie Mac has published extensively on how low down payment conventional programs were built specifically to help qualified buyers compete without years of extra saving (freddiemac.com).
What’s Motivating Clermont County Buyers This Year
Most first-time buyers I talk to aren’t chasing a dream house — they’re chasing stability. A few patterns come up again and again:
- Tired of rent increases with nothing to show for it
- Wanting a yard, garage, or extra bedroom their current rental doesn’t offer
- Ready to stop moving every lease renewal
- Wanting predictable, locked-in housing costs instead of a landlord’s annual adjustment
None of that requires a huge income jump — it requires the right loan structure and a plan.
What First-Time Buyers Are Looking For
Across Milford, Batavia, Amelia, and Union Township, the homes generating the most first-time buyer interest tend to share a few features: manageable square footage, a low-maintenance yard, an attached garage, and a layout that doesn’t need immediate renovation. Ranch and split-level homes built from the 1960s-1990s show up often on East Side first-time buyer searches, simply because they tend to fit this budget range and don’t require major systems work right out of the gate.
Local Market Snapshot: Clermont County Right Now
Clermont County gives first-time buyers something a lot of close-in city neighborhoods can’t: variety. You’ve got the walkable downtown and river access around Milford, the Little Miami Scenic Trail running through Loveland for commuters who bike, East Fork State Park for weekend outdoor time, and easy shopping and dining corridors around Eastgate and Amelia. Commuting into downtown Cincinnati typically runs along SR-32, US-50, or I-275, depending on where you land, so it’s worth test-driving your commute before you fall in love with a specific street.
Curious what’s actually available in your price range right now? Browse Clermont County homes under $300K → — it updates in real time, so you can see exactly what 3% down could put you into this week.
Financing a Home With 3% Down: What You Need to Know
Conventional 97 vs. FHA
A Conventional 97 loan allows 3% down and is often the better fit for buyers with solid credit, since it can drop mortgage insurance once you hit 20% equity. FHA loans require a slightly higher 3.5% down but allow lower credit scores and more flexible debt-to-income ratios. Neither is automatically “better” — it depends on your credit profile and goals.
Credit Score & Debt-to-Income
Conventional 97 loans generally want a credit score in the 620+ range, while FHA will work with scores as low as 580. Lenders also look closely at your debt-to-income ratio, so paying down a car loan or credit card balance before applying can meaningfully change what you qualify for.
Private Mortgage Insurance (PMI)
With less than 20% down, you’ll pay PMI (or FHA’s mortgage insurance premium) until you build enough equity. It’s an added monthly cost, but it’s the trade-off that makes the lower down payment possible in the first place — and it typically falls off a conventional loan automatically once you reach 20% equity.
Down Payment Assistance Programs
Ohio buyers also have access to state-level assistance through the Ohio Housing Finance Agency, which can help cover part of the down payment or closing costs for eligible first-time buyers. A knowledgeable local lender can tell you quickly whether you qualify.
Actionable Tips to Get Mortgage-Ready
- Get pre-approved before you start touring homes — not just pre-qualified
- Ask your lender to run numbers for both Conventional 97 and FHA so you can compare real payments
- Budget for closing costs separately — typically 2-5% on top of your down payment
- Avoid opening new credit accounts or making large purchases while your loan is in process
- Ask about Ohio down payment assistance programs before you assume you don’t qualify
The Pro REALTOR® Strategy Most First-Time Buyers Miss
Here’s what a lot of buyers overlook: a 3%-down offer doesn’t have to look weaker to a seller than a 20%-down offer. A clean, fully underwritten pre-approval letter (not just a quick pre-qual) signals to a seller that your financing is solid, regardless of your down payment size. On top of that, in the right market conditions, you can often negotiate seller-paid closing costs instead of asking for a lower price — which stretches your cash further without making your offer look less competitive. Most buyers never ask; the ones who do often get it.
Frequently Asked Questions
Can I really buy a home with only 3% down?
Yes. Conventional 97 loans allow 3% down for qualified buyers, and FHA loans allow 3.5% down with more flexible credit requirements.
What loan programs offer 3% down payments?
The main options are the Conventional 97 loan (3% down) and FHA loans (3.5% down). Your lender can tell you which one fits your credit and income profile best.
Do I need perfect credit to qualify for a low down payment loan?
No. Conventional 97 typically wants a 620+ credit score, and FHA will work with scores as low as 580 in many cases.
Will I have to pay PMI with 3% down?
Yes, you’ll pay mortgage insurance until you build enough equity — usually 20% — at which point it can be removed on a conventional loan.
What’s the difference between FHA and a Conventional 97 loan?
FHA requires slightly more down (3.5% vs. 3%) but allows lower credit scores. Conventional 97 can shed mortgage insurance sooner once you build equity.
Are there down payment assistance programs in Clermont County?
Ohio offers state-level down payment and closing cost assistance programs for eligible first-time buyers through the Ohio Housing Finance Agency — worth asking your lender about before you assume you don’t qualify.
How much house can I actually afford with a 3% down payment in this market?
It depends on your income, debts, and the loan program, but as the examples above show, 3% down on a $280,000-$350,000 home in Clermont County typically means $8,400-$10,500 in cash to close — well within reach for many first-time buyers once they see the real math.
Bottom Line
Buying your first home doesn’t have to mean waiting years to save 20% down. Between Conventional 97, FHA, and Ohio’s down payment assistance options, a 3% down payment in Clermont County is realistic for a lot of renters who assumed it wasn’t. The National Association of REALTORS® has tracked this shift nationally for years — first-time buyers increasingly aren’t the ones putting 20% down.
If you’ve been sitting on the sidelines waiting for “someday,” let’s find out what today actually looks like for you.
📞 Schedule a free 30-minute consultation — we’ll map out your exact numbers.
🏡 Find out what your home is worth if you’re buying and selling at the same time.
🔍 Search Clermont County homes for sale right now.
📬 Subscribe to the blog for weekly East Side market updates.
Grab the full breakdown in the 2026 Home Buyer Guide, or get mortgage-ready step by step with the 30 Days to Home Readiness checklist.
